Nexo Card Review: Spending Against Your Crypto Works, Until a Price Drop Makes It Expensive
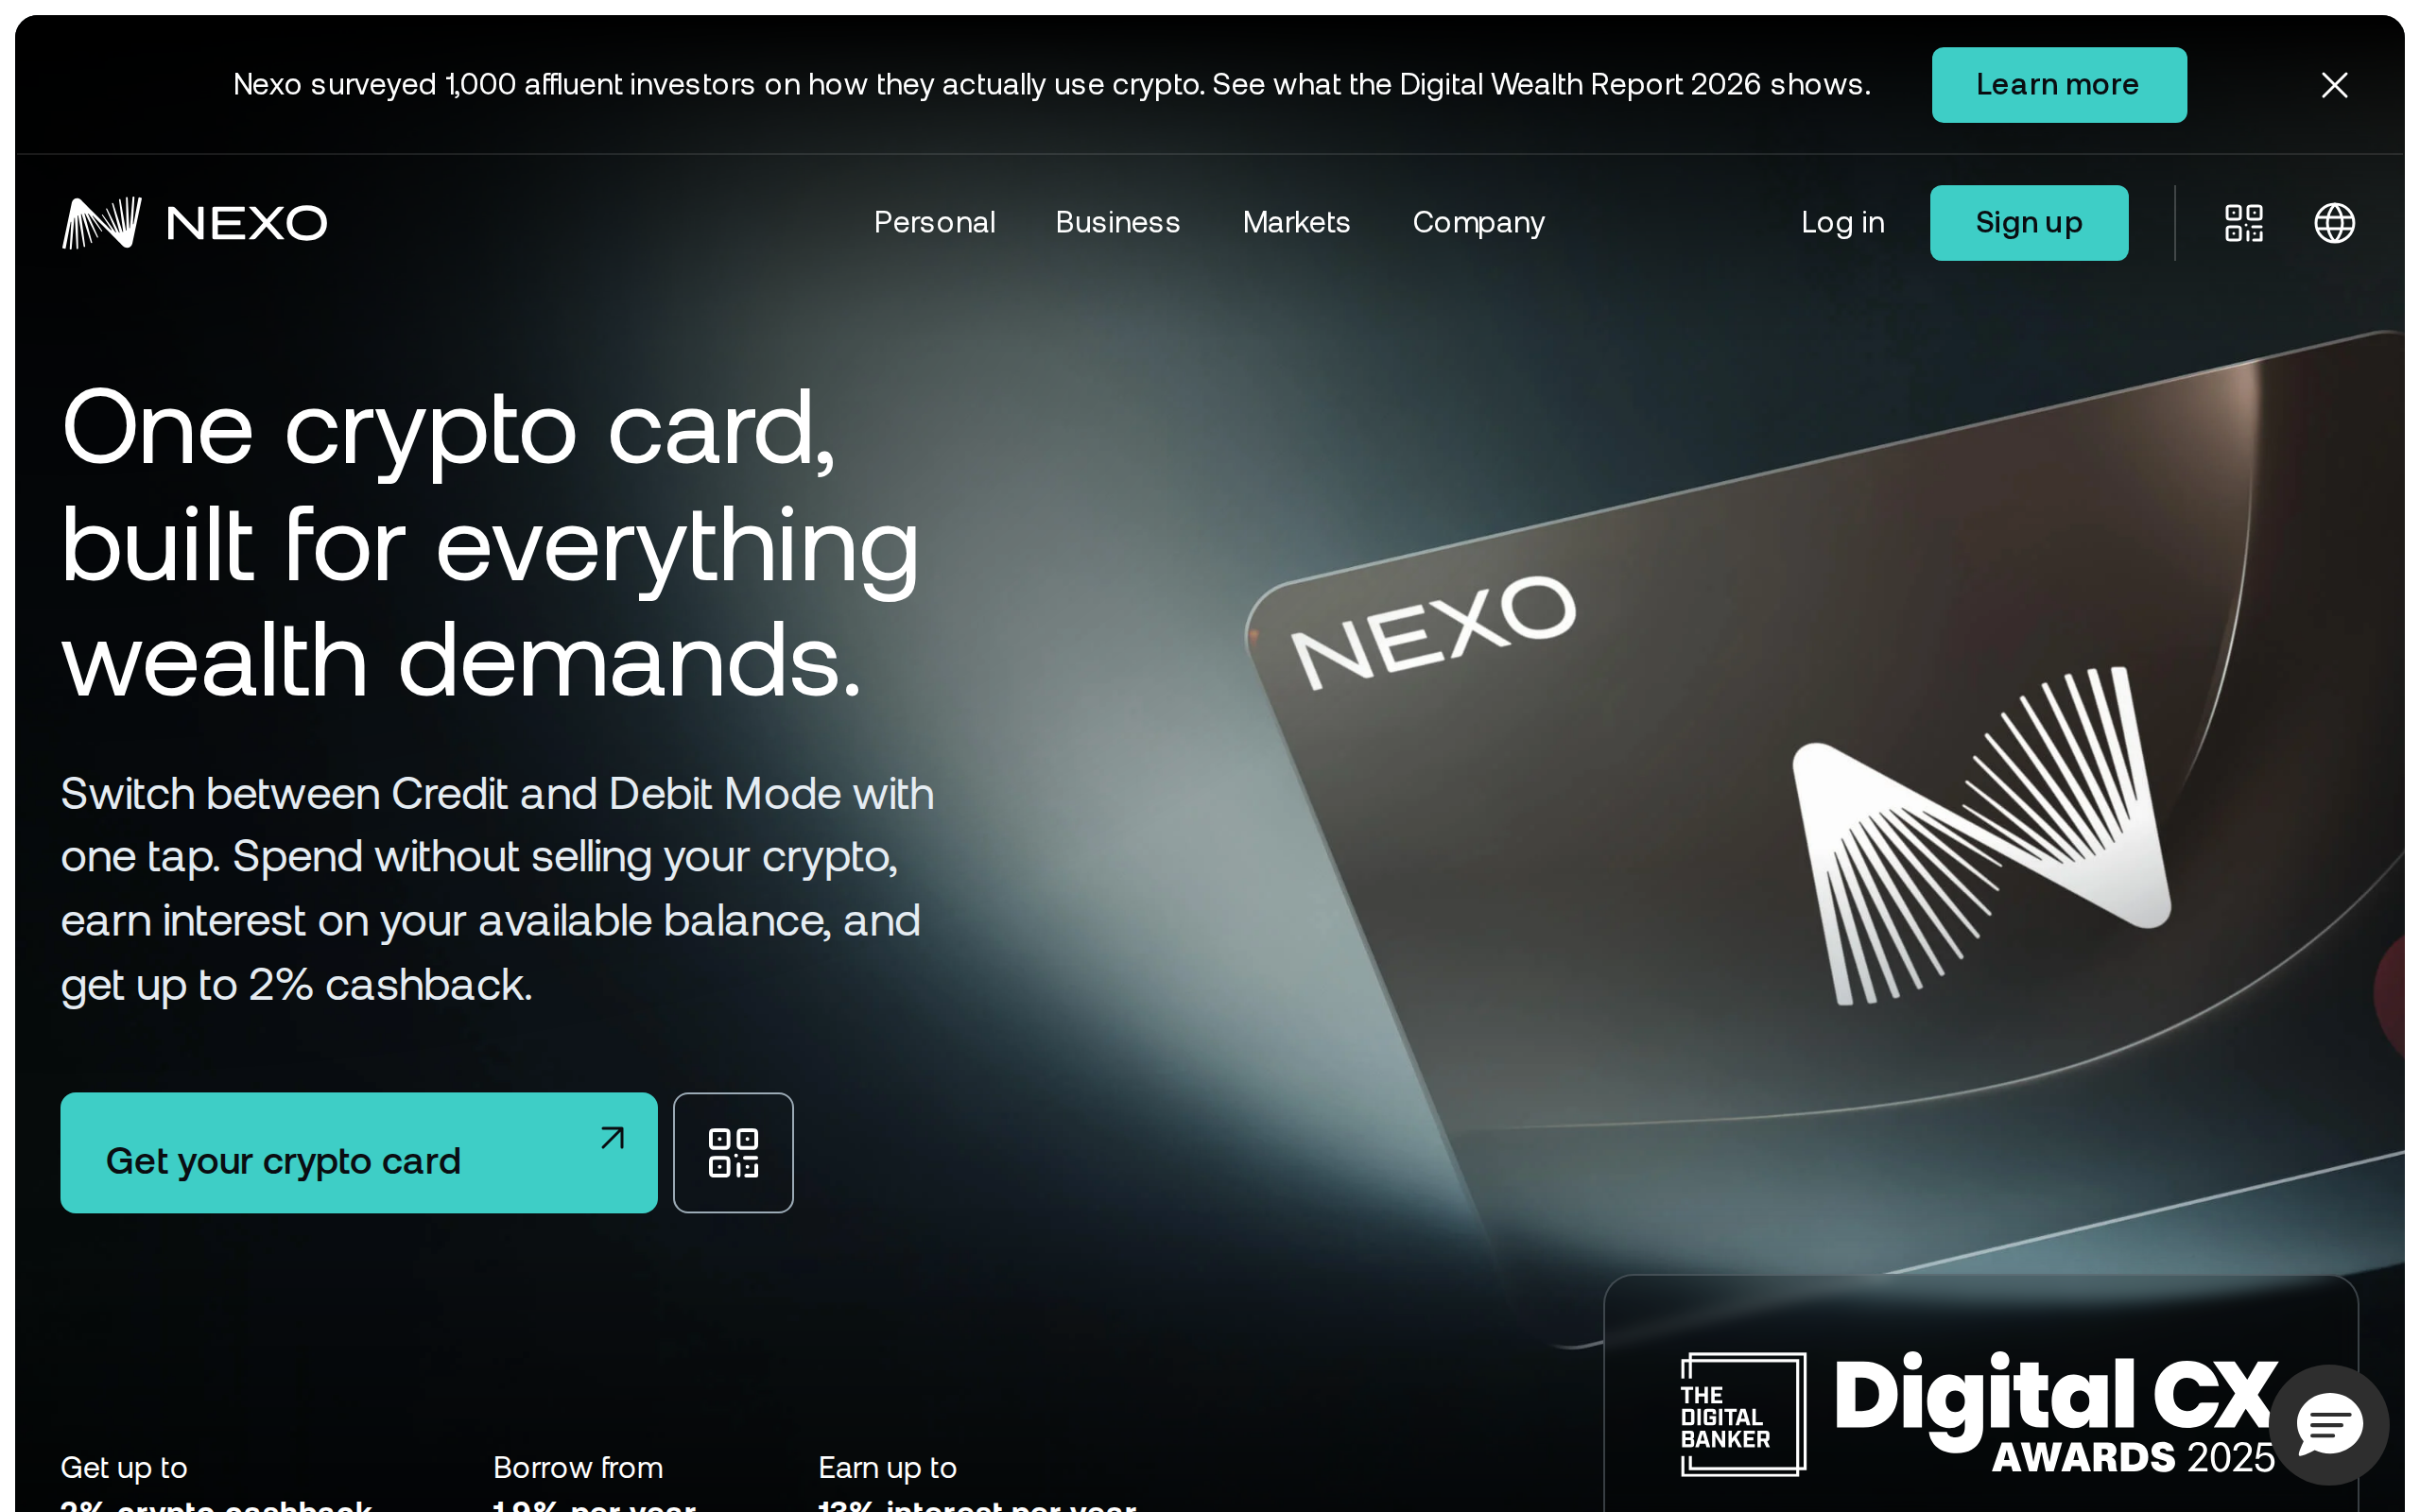
The Nexo Card spends in debit or credit mode with no monthly fee and up to 2% cashback. We checked the loyalty tiers, the 1.9% headline rate and the liquidation risk that sits behind every credit-mode swipe.
The verdict
The Nexo Card is a real convenience: one card that spends your crypto directly or borrows against it, with no monthly fee. But the best numbers, 2% cashback, 1.9% borrowing and 2,000 euros of free ATM cash, all sit at the Platinum loyalty tier, and credit mode adds liquidation risk that a normal debit card never has. It is only offered in the EEA and UK, and is a poor fit for anyone who cannot watch collateral.
Best for European long-term holders who want to spend without selling and can monitor collateral
Pros
- No monthly, annual or inactivity card fees
- Credit mode lets you spend without selling holdings, with cashback up to 2%
- Foreign exchange is 0.2% on weekdays inside the EEA, UK and Switzerland
- Switching between credit and debit mode takes one tap in the app
Cons
- Best cashback, rate and ATM limits require the Platinum loyalty tier
- Credit mode can trigger partial liquidation if collateral value falls
- Debit mode earns no cashback, and credit-mode cashback needs a $5,000 balance
- Only available in the EEA and UK, with no US launch
A crypto card has one job: turn the coins you hold into coffee money without a tax event or a bad exchange rate. Most do it by selling. The Nexo Card does it two ways, and the second is the one that deserves caution.
In debit mode it spends your balance, and the app sells assets at the moment of payment. In credit mode it never sells. It lends you money against your crypto, and you owe it back with interest. Nexo's pitch is that you keep your Bitcoin and still pay for dinner.
That is true. It is also the whole risk.
Credit mode is a loan, not a card feature
Borrowing against crypto is simple until the collateral falls. Nexo's own card page quotes borrowing "from 1.9% per year" with no credit check, and the flexible repayment is a real benefit. The 1.9% belongs to the top loyalty tier, though.
Reviewers who have gone through the tiers put the Base rate far higher: Coin Bureau quotes 17.9% at Base, another review quotes 13.9%. We could not pin the figure down from Nexo's public pages, so look inside the app before you borrow. What matters is the spread between those numbers.
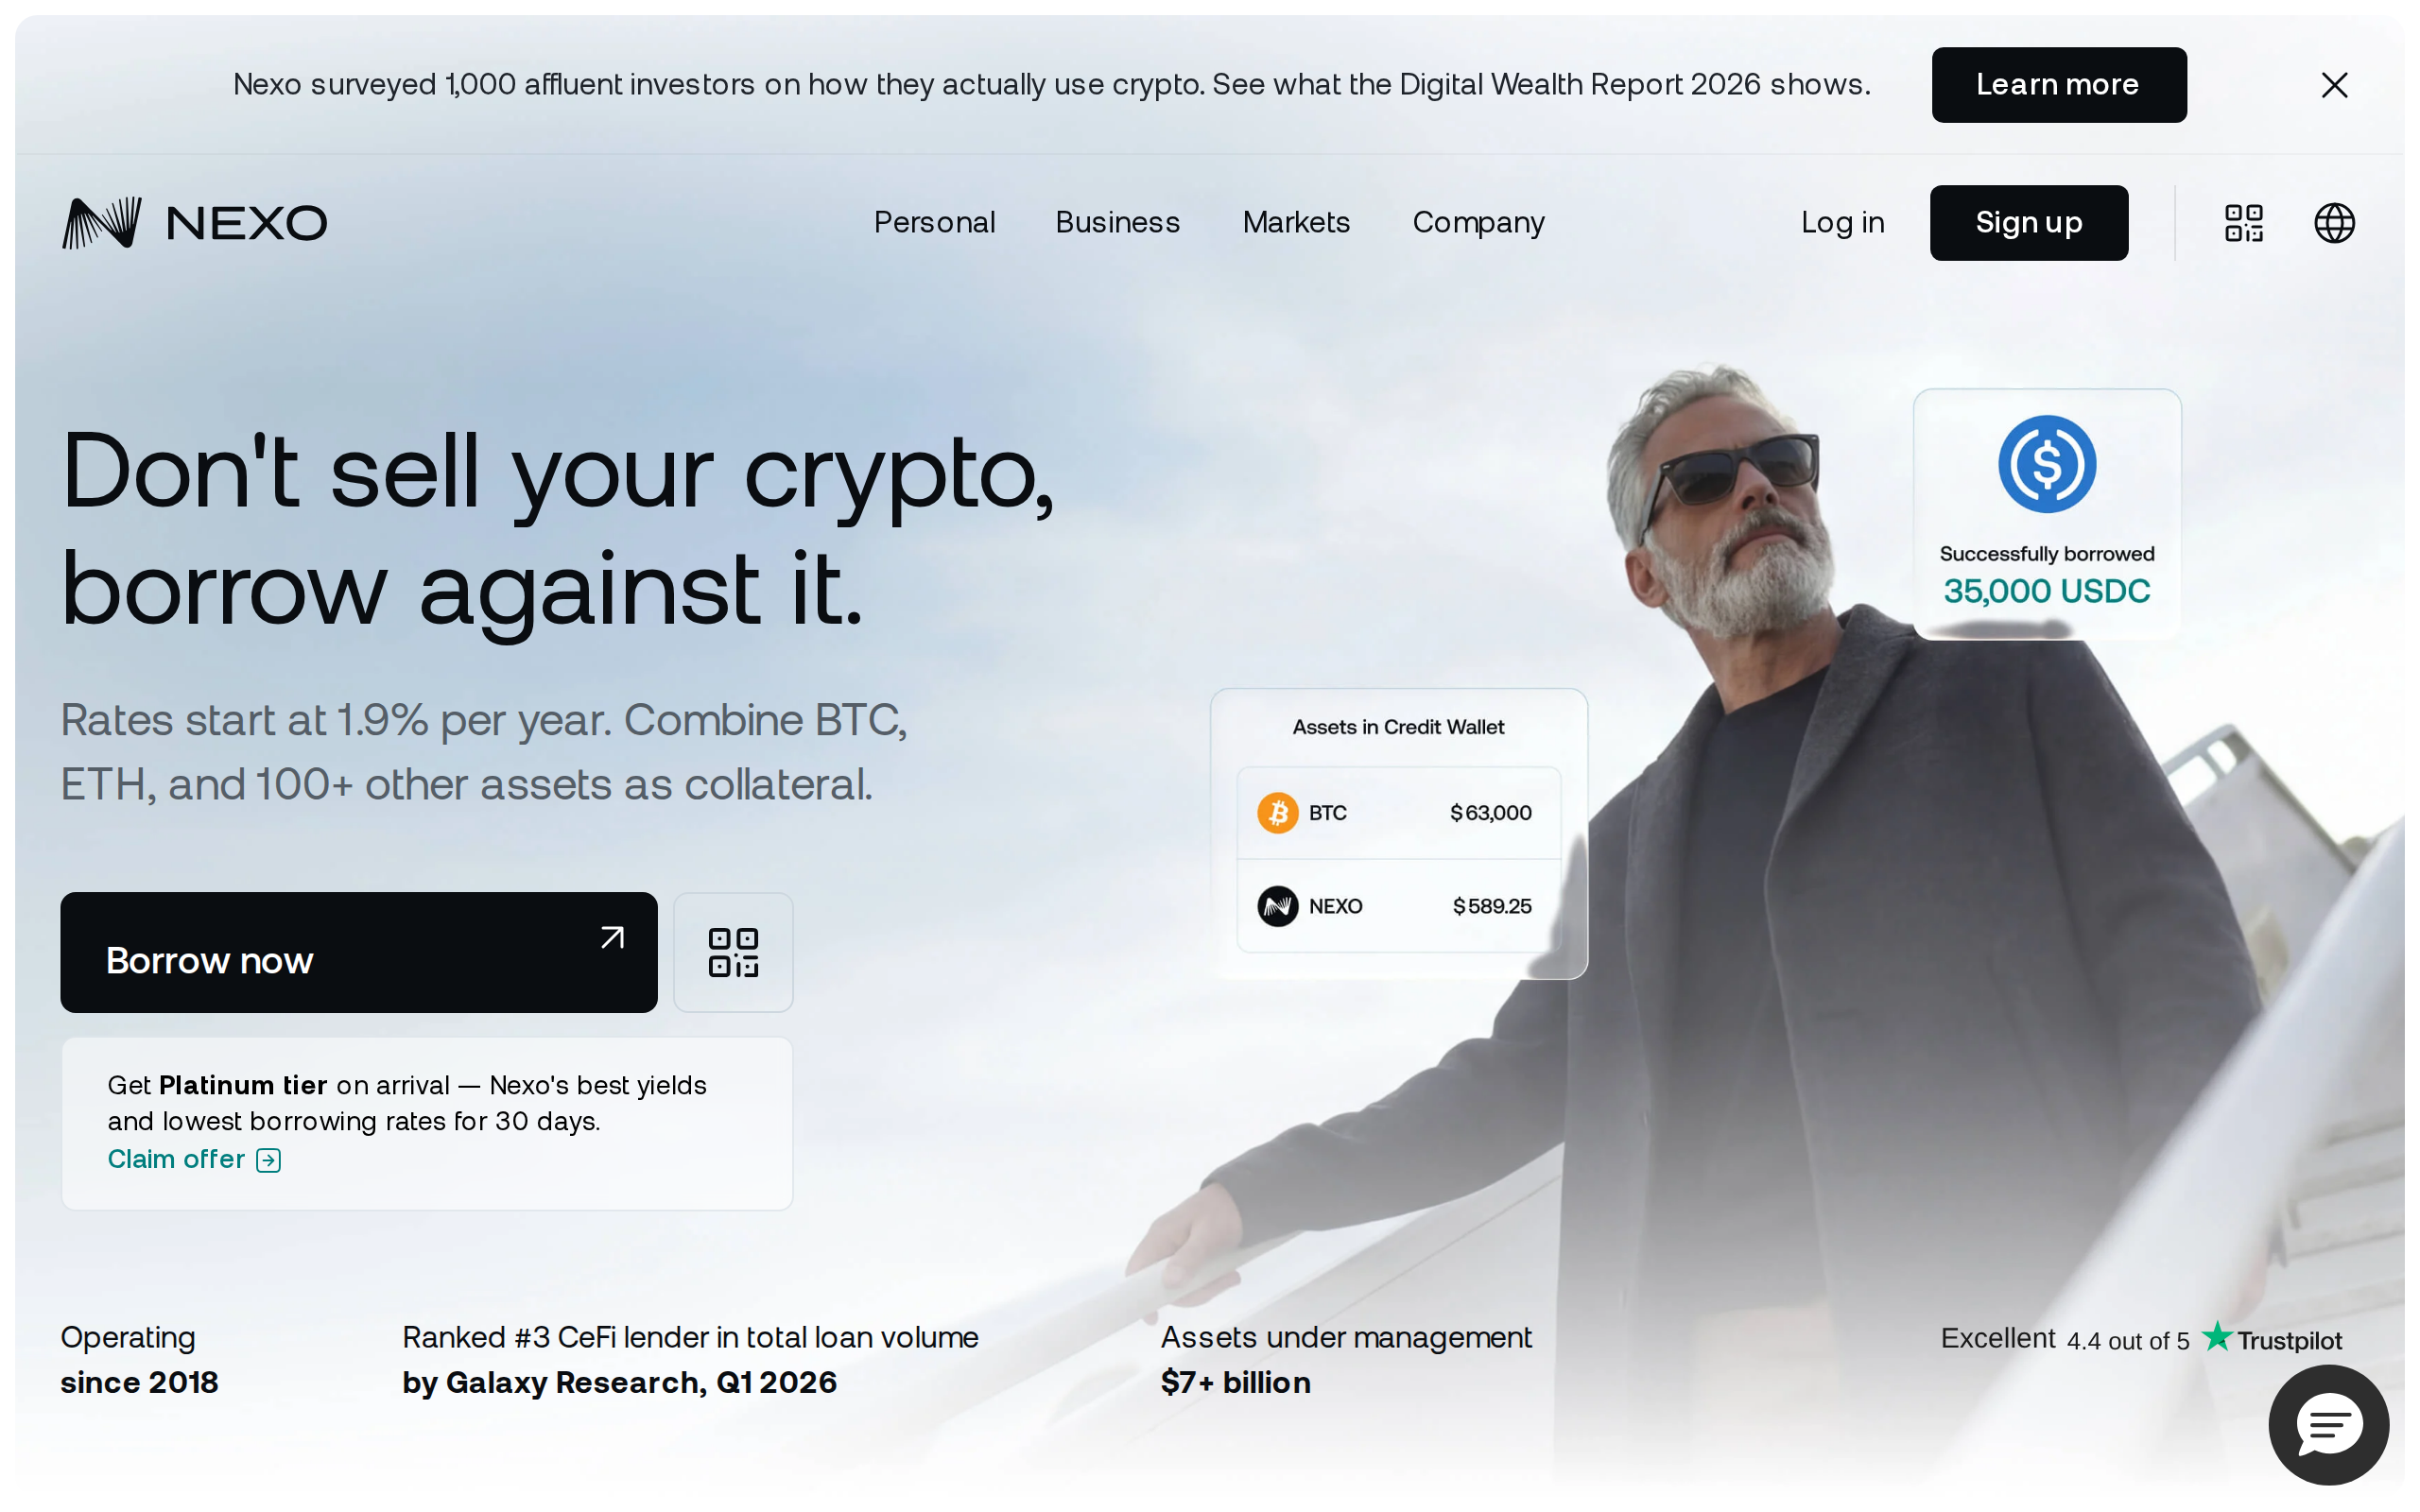
If the loan-to-value ratio climbs, Nexo can partly liquidate your collateral. Third-party reviews put that line near 83% LTV, with up to 90% allowed on stablecoin collateral. Treat those as indicative: the number can change, and we would not run anywhere near it. A 30% drop in a volatile coin can turn a comfortable loan into a forced sale, at the worst price, which is exactly what spending against crypto was meant to avoid.
A plain debit card cannot do that to you. If you want the benefit of borrowing, keep the loan small against a large pile, and never top up collateral in a panic.
What the loyalty tiers do to the headline numbers
The card has no monthly, annual or inactivity fee, which is the good news. The rest is tiered, and the tiers depend on how much NEXO token you hold as a share of your portfolio.
Base: 0.5% in NEXO or 0.1% in BTC, 200 euros of free ATM cash a month.
Silver: 0.7% or 0.2%, 400 euros.
Gold: 1% or 0.3%, 1,000 euros.
Platinum: 2% or 0.5%, 2,000 euros.
Cashback applies to credit mode, and Nexo's page ties it to a $5,000+ balance. Platinum reportedly needs NEXO to make up 10% or more of your portfolio. That is not a perk, it is a position: you have to hold a single exchange token to get the rate in the advert.
Fees outside the headline
Foreign exchange is cheap at home and ordinary abroad. Weekday FX is 0.2% in the EEA, UK and Switzerland, and 2% elsewhere. Weekends cost more: 0.7% and 2.5%. ATM withdrawals are free to the tier limits, then 2% with a 1.99 minimum.
Nothing here is hidden, but the spread between 0.2% and 2.5% is wide enough to matter if you travel on weekends. Compare it with a normal bank card, which often charges less on foreign spending and carries no liquidation risk.
Using it day to day
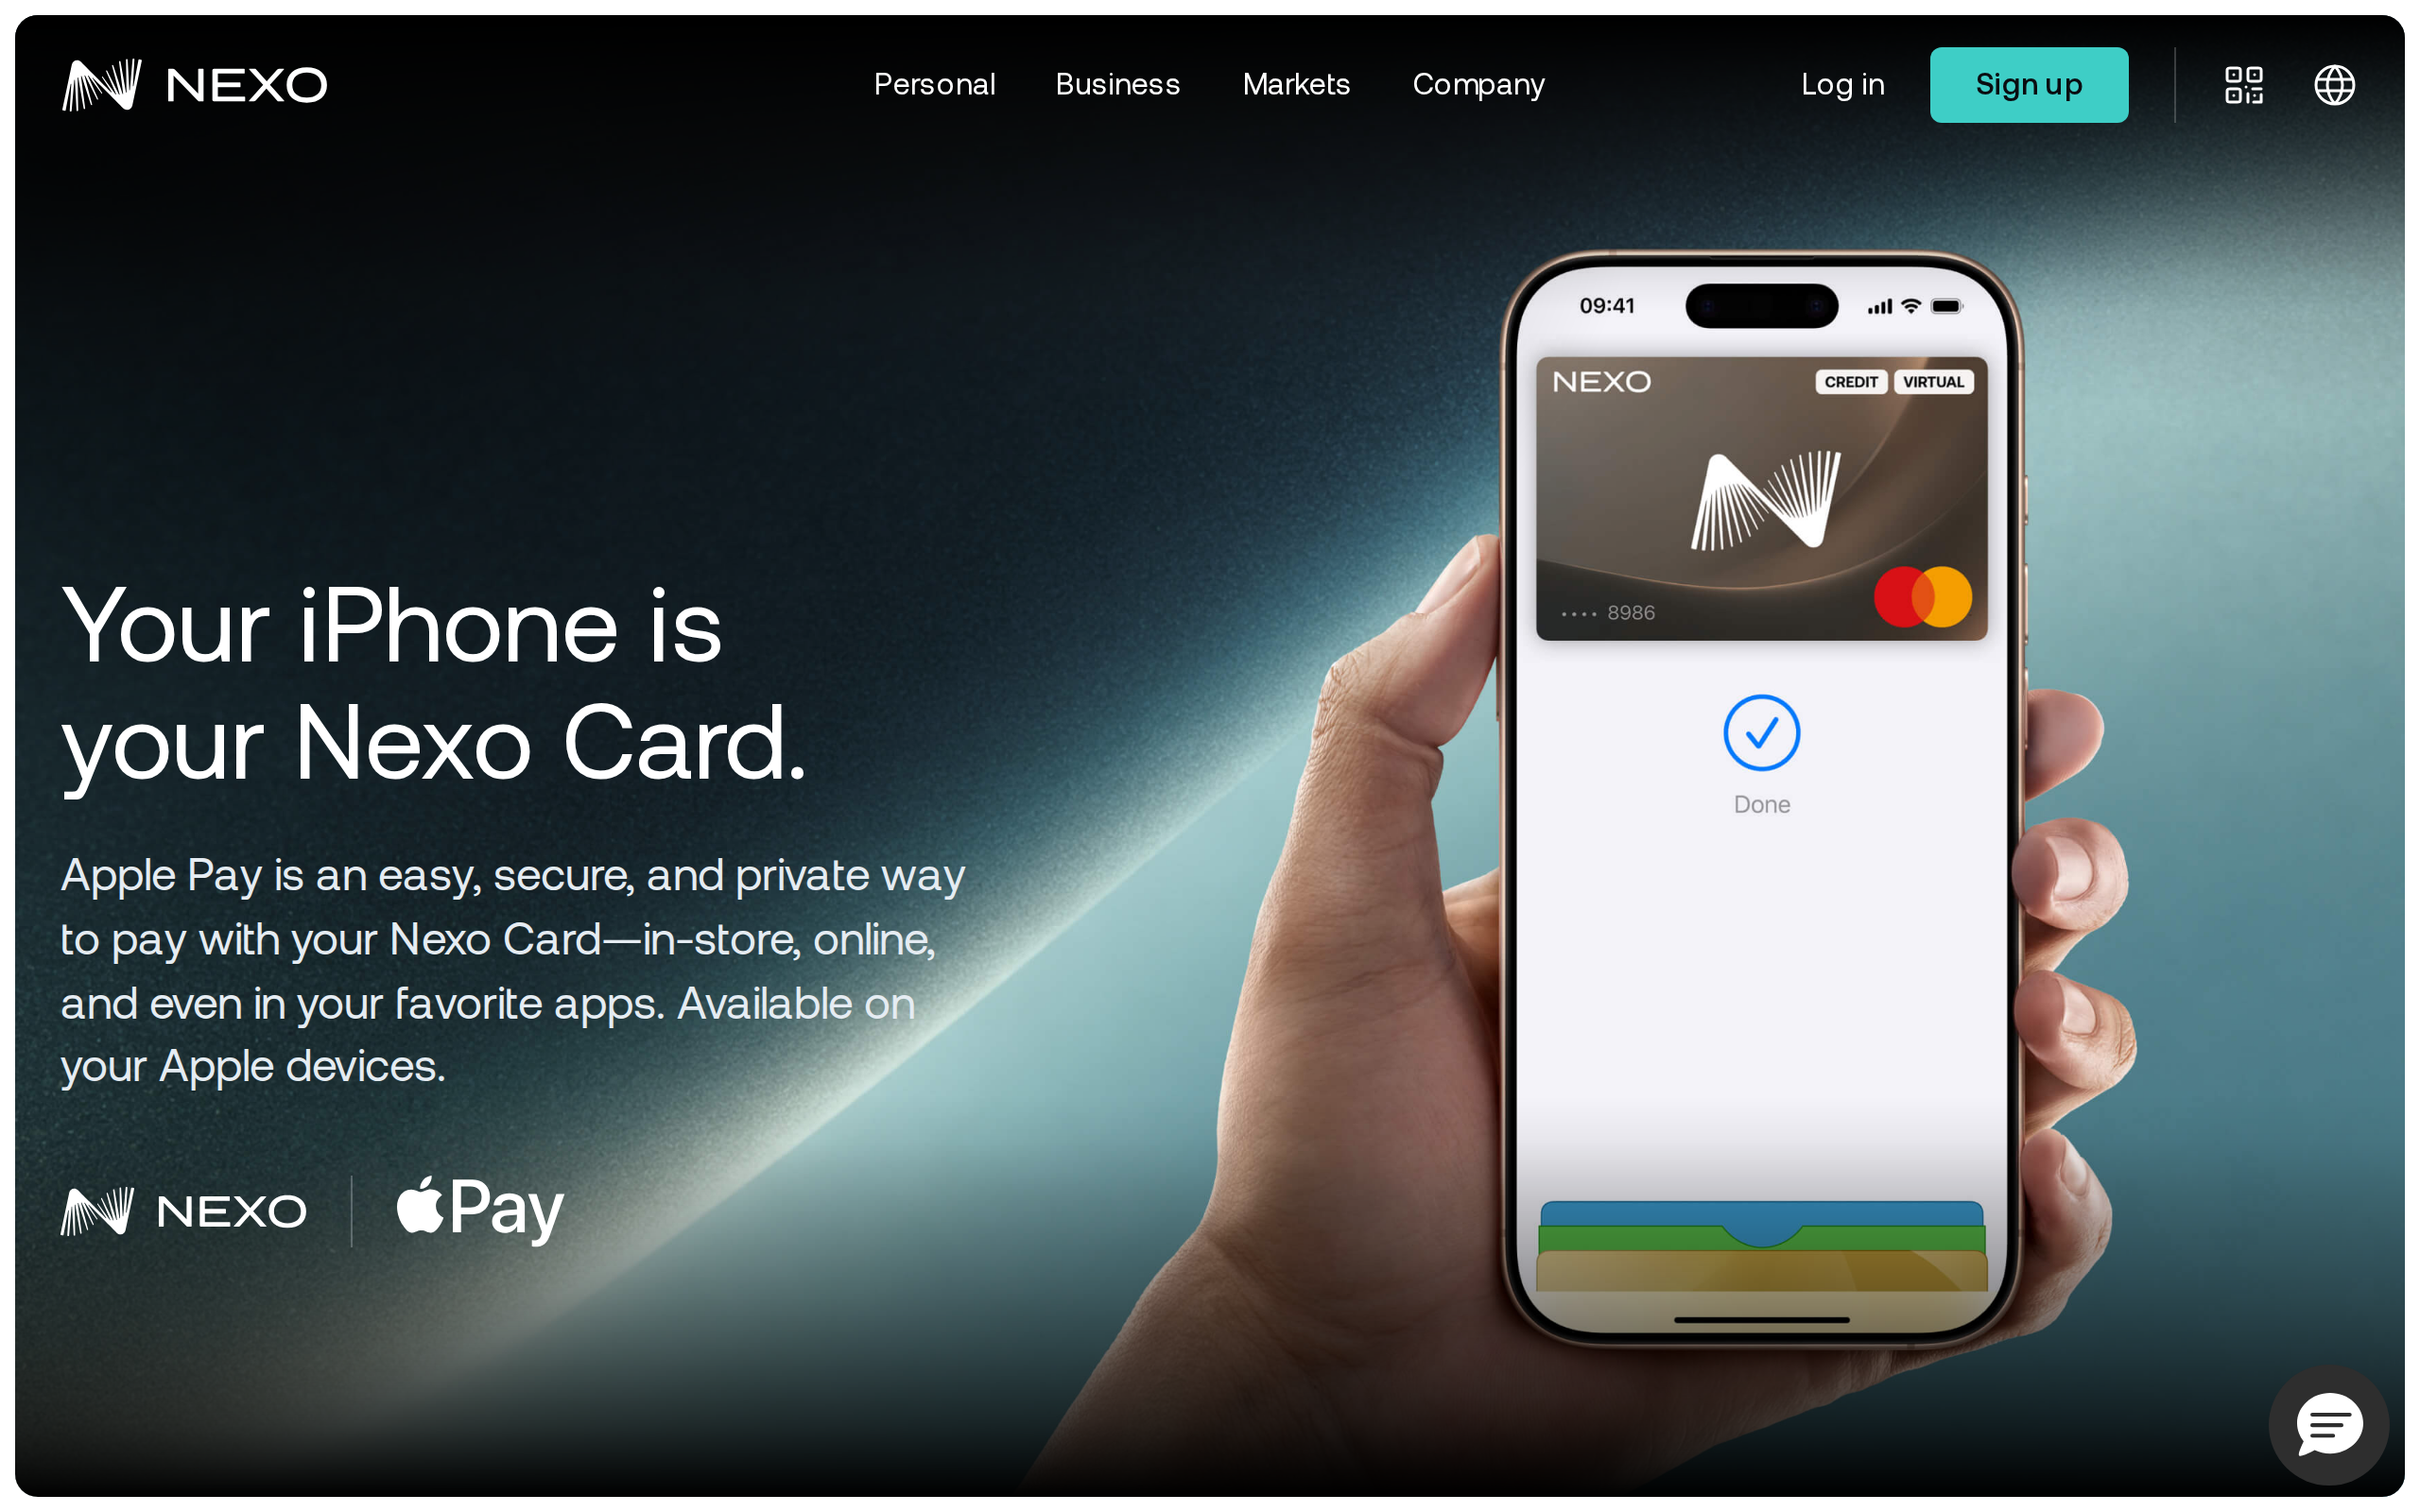
The card is Mastercard, issued by DiPocket UAB, and it works in Apple Pay without waiting for plastic. Nexo's page says "your iPhone is your Nexo Card", and a virtual card can be activated straight away.
Availability is the first filter. The card is for "selected European countries", meaning the EEA and UK. There is no US launch, so if you live elsewhere, skip it.
Trust is the second. Nexo is a custodial lender, so your collateral sits with the company. Its regulatory history includes a 2023 settlement with US regulators over its earn product, which is public record. That is not a reason to rule it out, but it is one to size your exposure.
Verdict
Choose the Nexo Card if you are a European holder who already uses Nexo, has a large balance, and wants a low-rate way to spend without selling. Use credit mode in small amounts, and check collateral on the app.
Skip it if you want a simple card, if your balance is under about $5,000, or if you would rather not hold NEXO to unlock the rate. For most people the plain debit mode, or an ordinary card, does the job with none of the borrowing risk. This is a review, not personal financial advice.
Specifications
- Card fees
- No monthly, annual or inactivity fee
- Modes
- Credit (borrow) and Debit (spend balance)
- Cashback
- 0.5% to 2% in NEXO, 0.1% to 0.5% in BTC
- Borrow rate
- From 1.9% a year (tier dependent)
- FX, weekday
- 0.2% EEA/UK/CH, 2% elsewhere
- FX, weekend
- 0.7% EEA/UK/CH, 2.5% elsewhere
- Free ATM per month
- 200 euros (Base) to 2,000 euros (Platinum)
- ATM fee over limit
- 2% with a 1.99 minimum
- Network and issuer
- Mastercard, issued by DiPocket UAB
- Availability
- EEA and UK only
As published by Nexo when we tested it.